This blog was written by Wouter van 't Grunewold, Market Intelligence Analyst, and Niek Poppelaars, Head Logistics & Industrial, at Savills the Netherlands
Logistics real estate: investment rises despite declining take-up. Savills Netherlands - Q1 2026
Dutch real estate investment volumes rebounded to €14.5 billion in 2025 (+19.1% year on year), supported by further policy rate cuts by the European Central Bank and a gradual stabilisation of capital markets. Despite persistent macroeconomic and geopolitical uncertainty, improving financing conditions and greater pricing clarity brought buyers and sellers closer together.
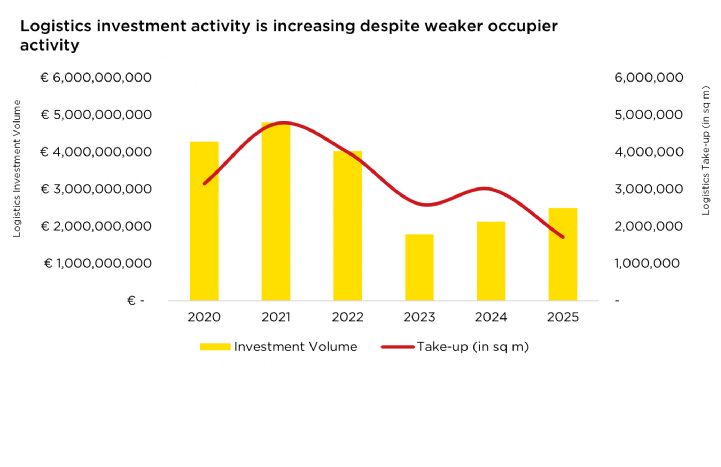
The logistics sector was a clear beneficiary of improving capital market conditions. Investment volumes rose by 16.7% compared to 2024 to €2.51 billion in 2025, even as occupier markets weakened. Logistics take-up declined amid trade volatility and cost pressures, highlighting a familiar cycle dynamic in which investors move ahead of leasing markets, guided by longer-term fundamentals rather than near-term uncertainty.
Capital markets move first
The divergence between investment and occupier activity reflects a familiar cycle dynamic: capital markets typically recover ahead of occupier markets. Investors are placing greater emphasis on medium- to long-term fundamentals rather than short-term volatility in leasing activity. In this context, logistics continues to stand out, supported by structural demand drivers despite near-term caution among occupiers.
The Netherlands occupies a pivotal position within Europe’s logistics network, located at the intersection of key north–south and east–west trade corridors. At the same time, evolving European trade policy and ongoing efforts to diversify trade relationships are reinforcing the country’s strategic relevance. Agreements and negotiations with regions such as South America (Mercosur) and India will support trade flows over the medium term.
This shift was already visible in 2025, with Dutch import and export volumes both increasing by 3.1% on an annual basis, while the share of US-related trade declined by 4.7% in the first ten months of the year.
Focus on core locations and quality assets
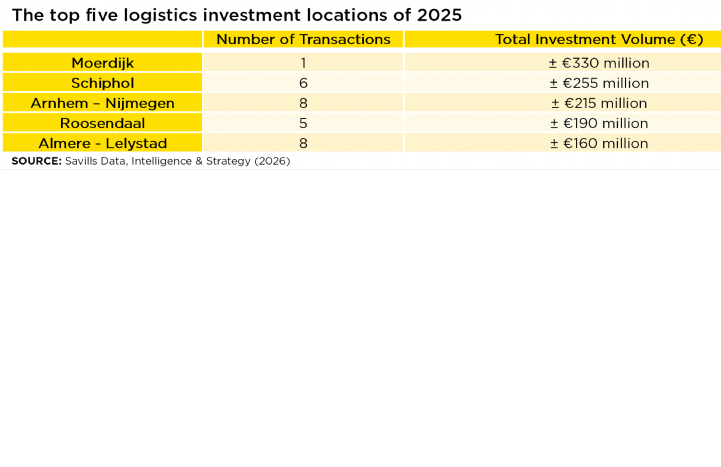
Investment activity in 2025 was concentrated. Approximately 58.5% of total logistics investment volume was transacted within the 12 largest logistics areas*, all located along the Netherlands’ main transport arteries and directly connected to the European hinterland. This concentration reflects a continued preference for liquidity, scale and long-term relevance.
Beyond location, asset quality played a decisive role. Transactions were predominantly focused on modern distribution centres, typically built post-2010, with average unit sizes typically ranging between 10,000 and 20,000 sq m.
A growing share of traded assets (24.8%) featured BREEAM certification. This not only aligns with investors’ ESG requirements but also enhances liquidity and marketability. Sustainable assets are better aligned with investment mandates and carry lower future retrofit risk, supporting long-term value.
The majority of assets (94.5%) were income-producing, often secured by leases to 3PLs, retailers or manufacturers. Purchaser demand was led by institutional investors, followed by private equity and high-net-worth capital. Notably, the share of foreign capital in logistics was higher than in any other Dutch real estate sector, underlining the Netherlands’ continued appeal as a core European logistics market.
This rebalancing between capital and occupier markets was also reflected in pricing, with prime logistics net initial yields remaining broadly stable at approximately 4.75% in 2025.
Outlook: fundamentals remain compelling
Although occupier markets experienced a temporary dip in 2025, the outlook for Dutch logistics remains constructive. Ongoing supply-chain centralisation, illustrated by large-scale consolidation strategies such as DSV’s operations in Moerdijk, continues to favour well-located, modern assets.
For investors, this is not a reason for caution but a moment for selective capital allocation. In a market characterised by structural demand, limited planning capacity and a relatively young, high-quality stock, opportunities lie in differentiation and asset quality.
Supported by strong infrastructure, a strategic location and a liquid, transparent investment market, the Netherlands remains one of Europe’s most resilient logistics investment markets.
*12 Largest Logistics Regions: Amsterdam, Bleijswijk-Waddinxveen, Breda-Oosterhout-Raamsdonkveer, Eindhoven, Moerdijk, Roosendaal, Rotterdam, Schiphol, Tilburg-Waalwijk, Utrecht-Nieuwegein, Venlo-Venray, Zaltbommel-Tiel-Geldermalsen.